Overview
Puype's career in finance and risk software goes back to FinArch (Financial Architects), the Belgian company he co-founded in 1997 with Dirk De Beule. FinArch built finance resource planning software that helped banks with regulatory compliance around IFRS, Basel II and liquidity risk.
Chris Puype is the chief executive and founder of ElysianNxt, a software company that builds real-time risk and finance solutions for financial institutions. He started the company with the aim of bringing real-time enterprise-wide finance and risk regulatory calculations to the finance industry, with more affordable software that lets firms react faster to changes in global compliance. ElysianNxt was founded in 2017 and is headquartered in Brussels, with offices in Bangkok and Jakarta, and employs between 51 and 200 people. Its .NXT platform covers IFRS 9, Basel IV, asset-liability management, data management, regulatory reporting, stress testing and model management, delivered as SaaS. Customers include Bank Sulselbar, an Indonesian regional development bank that selected the company in 2025 to implement PSAK 71 and PSAK 413, and Creditspring, a UK lender that uses IFRS9.NXT for expected credit loss and effective interest rate calculations. Chartis Research named ElysianNxt a Category Leader 2025 in retail and wholesale credit risk management.
Career history

Insights & ideas
The through-line
Across his posts, Chris Puype keeps returning to one architectural idea: that credit risk, IFRS 9, Basel RWA and stress testing should live on the same governed platform instead of being stitched together through data movement between systems [1][9][15]. That conviction expands over time from a platform-design argument into a broader claim about how risk functions should operate under uncertainty, whether that uncertainty comes from climate and nature-related risks [5], from regulatory delay debates like FRTB and the Output Floor [8][12], or from the rise of agentic AI in banking [10]. Running alongside this is a second, sharper thread: impatience with claims that aren't backed by production-scale proof, whether that's a bank's capital buffer, an AI demo, or a regulatory "level playing field" argument [8][12][13].
On unifying the platform
Puype's core pitch is that asking a new question of a risk system should not require an ETL cycle. "For years, asking your credit risk system a new question meant moving data. Extract it. Transform it. Load it into another system. Run another batch. Reconcile the results." [1] His alternative: "If Credit Risk Modelling, IFRS 9 ECL, Basel RWA and Stress Testing & Forecasting operate on the same governed platform, you can keep the portfolio where it is and simply change the assumptions." [1] He frames this explicitly as a shift in mindset: "Stop moving data. Start moving risk assumptions" [1]. The same instinct shows up in his description of internal and regulatory models: "Internal models and regulatory models don't have to live in separate worlds." [9]
On proof over promises
Puype is consistently skeptical of claims that haven't been tested under real volumes. "In technology, it has never been easier to look impressive. AI can generate content in seconds. Demos can be carefully controlled. Screenshots can show only the best-case scenario." [13] For him the real test is production scale: "Can the platform process millions of contracts? Can it scale as demand grows? Can it continue delivering results when complexity increases?" [13] He backs this with concrete figures: "reduced processing times from 24 hours to one," "processed three million contracts in 12 minutes," and "maintained calculation times within an hour despite 900% volume growth" [13], summarized as "Claims are easy to make. Results are harder to fake." [13] The same challenge-us-directly posture appears when he invites clients to test the platform on their own data: "Give us the question and the data. We'll run it." [1]
On regulatory shortcuts
Puype pushes back hard on what he sees as regulatory retreat dressed up as pragmatism. On the EU's FRTB delay, he quotes Alain Papiasse approvingly ("We know there is a wake-up call. But everyone has a different clock." [8]) before delivering his own verdict: "Delay FRTB if you must. Just don't mistake 'following the US' for a strategy. The rules will land. The banks that are ready will have the advantage." [8] On the Output Floor debate he is even more direct: "Blaming the Output Floor for Europe's banking competitiveness gap is like blaming the scoreboard for the result." [12] He argues the real fixes lie elsewhere: "Fix Pillar 2 overlap. Complete the Banking Union. Strip out reporting that's purely operational cost with zero supervisory value." [12] and warns that "Weakening the floor doesn't make European banks more competitive. It makes them less comparable" [12].
On emerging and underestimated risks
Puype treats stress testing as only as good as what it targets. "Stress testing only works if you're stressing the right things." [5] He cites the ECB's view that "physical and nature-related risks are 'very likely being underestimated'" [5] and notes that "many banks are still building the data, models, and governance frameworks needed to assess them properly" [5]. He extends the same forward-looking lens to AI, describing agentic systems as a shift from insight to execution: "For years, AI has helped banks make decisions. The next step is letting it execute them." [10] He flags architecture as the binding constraint: "An AI agent is only as effective as the systems it can access." [10], while acknowledging "new challenges around governance, explainability, control, and accountability" [10].
From the stage
On the ElysianNxt Podcast, Puype goes into specifics that his written posts don't cover. In Episode 4 he discusses a white paper co-authored with Avantage Reply on "the risk function of the future," built from a CRO survey identifying pain points for chief risk officers [14]. In Episode 13 he walks through the Dragon Release (R10) in product detail: a lifetime PD at origination calculator for IFRS 9 that compares probability of default at reporting date versus origination, improved overlay functionality, Basel 4 revisions support with flexible CRM configuration, a new credit spread risk in the banking book component required by EBA guidelines, and enhanced reporting with data lineage tracking [15]. In Episode 14, hosting Pete Milla, the discussion surfaces the view that "stress testing means different things to different organizations" and that "banks have historically underinvested in proper stress testing capabilities" [16], a diagnosis more granular than the general stress-testing critique in his written posts.
Takeaways
- Push vendors and internal teams to justify why credit risk, IFRS 9, Basel RWA and stress testing sit on separate systems rather than one governed platform [1][9].
- Treat any AI or platform performance claim as unproven until it's shown under real production volumes, not demos [13].
- Don't treat regulatory delays (FRTB, Output Floor) as strategy-neutral; ask whether the underlying risk has actually decreased [8][12].
- Assume nature and climate risks are currently underestimated in stress testing frameworks and check whether data, models and governance are mature enough to capture them [5].
- When evaluating agentic AI initiatives in banking, examine the surrounding system architecture and governance controls, not just the model's decision-making capability [10].
- For IFRS 9 practitioners, watch for tooling that compares lifetime PD at origination versus reporting date as a way to isolate credit risk migration [15].
Media & appearances
- ElysianNxtYouTubeElysianNxt Podcast EP14: The Elephant in the Stress Testing RoomChris Puype hosts Pete Milla, director of risk, to discuss stress testing in financial institutions, with Milla explaining that stress testing means different things to different organizations and that banks have historically underinvested in proper stress testing capabilities as part of their risk management frameworks.
- ElysianNxtYouTubeElysianNxt Podcast Episode 4: The Risk Function of the FutureChris Puype discusses a white paper co-authored by Elysian NXT and Avantage Reply on the risk function of the future, which originated from a CRO survey identifying pain points for chief risk officers in financial institutions.
- ElysianNxtYouTubeElysianNxt Podcast EP13: ElysianNxt Dragon Release (R10)Chris Puype discusses the Dragon Release of ElysianNxt's flagship products, highlighting new features including a lifetime PD at origination calculator for IFRS 9 users that compares probability of default at reporting date versus origination to help identify credit risk changes. He also covers improvements to overlay functionality, new Basel 4 revisions support with flexible CRM configuration, and a newly introduced credit spread risk in the banking book component required by EBA guidelines, along with enhanced reporting capabilities and data lineage tracking across the platform.
In the news
- Credit risk shouldn’t sound like five orchestras playing at once. In many banks, the same exposure is being looked at across IFRS 9, Basel RWA, credit risk modeling, stress testing, and climate risk — often through separate systems, with data moving between them and results needing to be reconciled. But these aren’t isolated questions. They’re connected parts of the same credit risk picture. And like any orchestra, it works better when everyone is reading from the same score. At ElysianNxt, the idea is to bring those pieces onto one
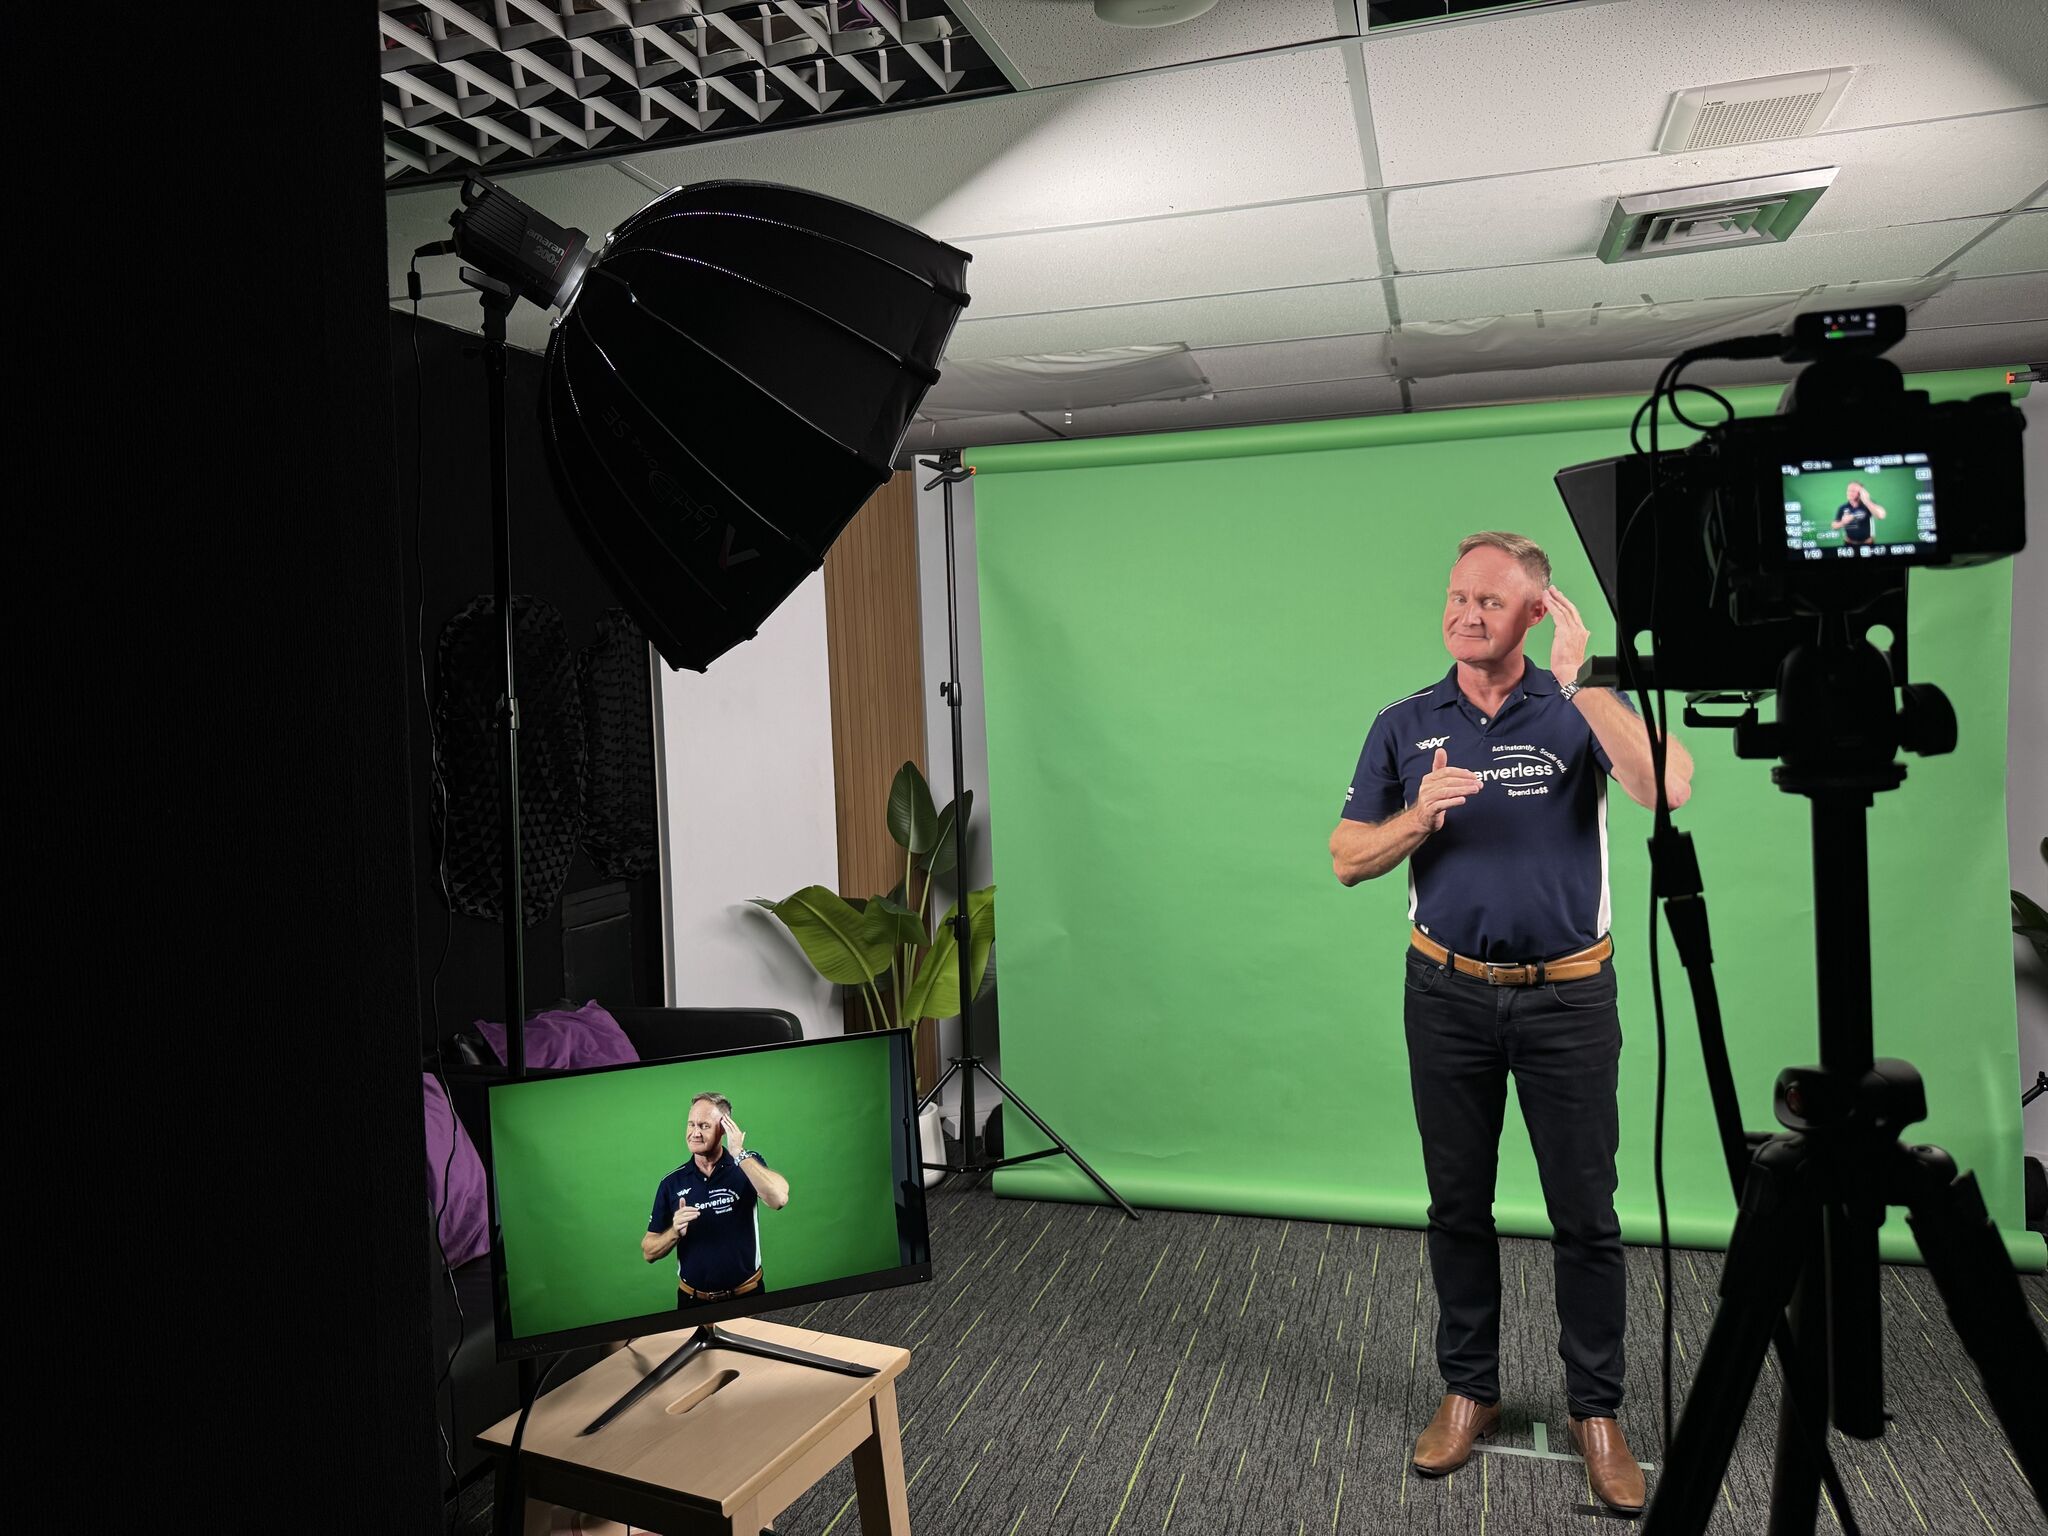
- Back in the studio Two videos on the menu today, built around two pretty simple ideas: One Credit Risk. One Platform. The same loan shouldn’t need five different systems to tell its story. And: Your AI can talk. Now give it something intelligent to talk to. Because conversational AI gets a lot more interesting when it can actually talk to your credit risk data, models, calculators and analytics. A double espresso, one last brush through the not too many hairs left , and we’re ready for action. Coming soon from ElysianNxt.
- Financial institutions are already making strategic decisions about which AI technologies they trust, how those environments are governed, and where their data may be processed. The risk platform should respect that choice. ElysianNxt didn't build our platform to compete with your AI stack. We built it to plug into it; through our ElysianNxt MCP, so your AI has the conversation, and asks our .NXT platform to do the calculation instead of guessing at one. That distinction matters more than people think. An AI-generated answer and an
- For years, asking your credit risk system a new question meant moving data. Extract it. Transform it. Load it into another system. Run another batch. Reconcile the results. All because somebody asked: “What if?” But why move the data at all? If Credit Risk Modelling, IFRS 9 ECL, Basel RWA and Stress Testing & Forecasting operate on the same governed platform, you can keep the portfolio where it is and simply change the assumptions. GDP down 2%? CRE values down 15%? Stop new CRE lending? Change the assumptions. Recalculate.
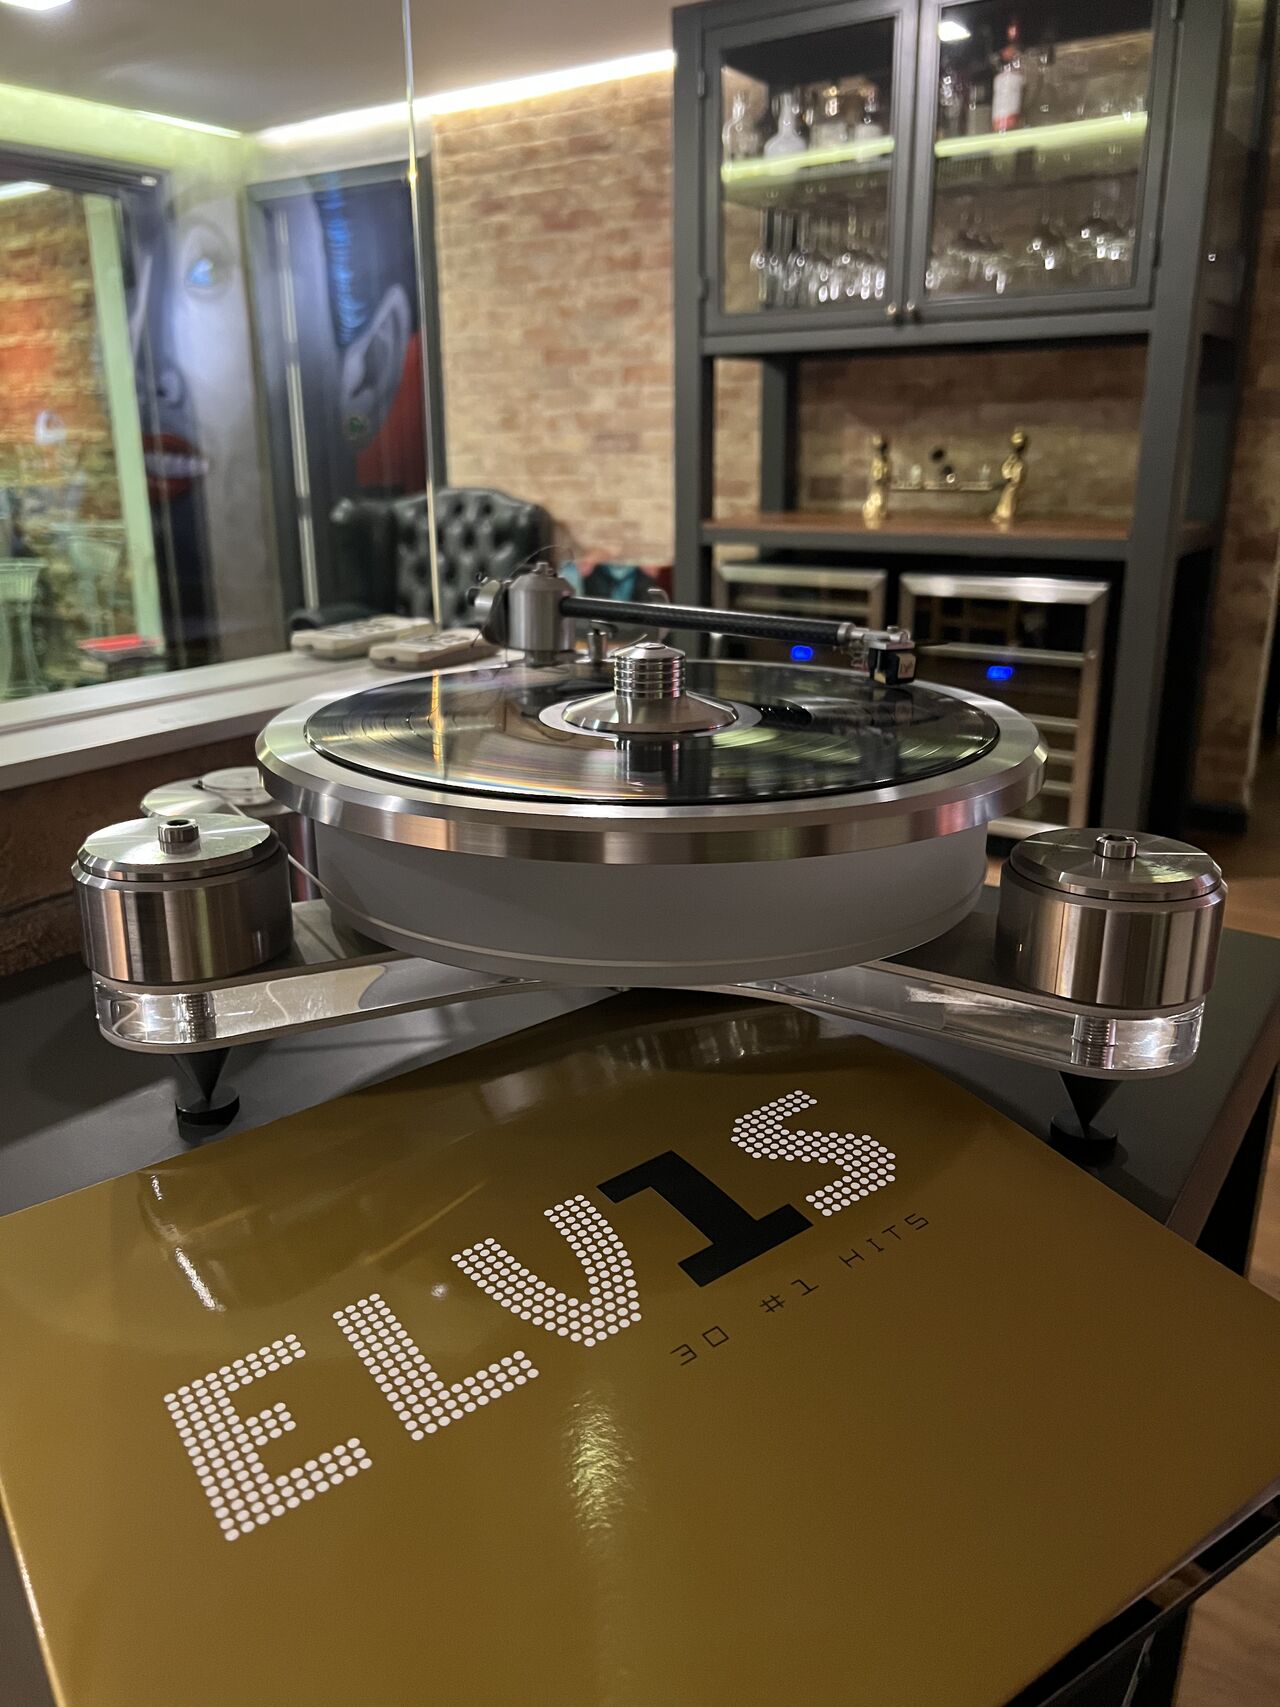
- A trip down memory lane… A few years late, I finally watched the fascinating movie Elvis, Return of the King with Tom Hanks playing Colonel Tom Parker. Parker was, in many ways, a marketing genius. He helped turn Elvis Presley into a global phenomenon but also suffocated some of his extraordinary raw talent. The movie sent me straight back to my record collection. Hearing that unmistakable voice on vinyl again reminds you why, almost half a century after his death, Elvis is still The King. Where were you on 16 August 1977 when you
- This book took me more than a year to finish. I simply fell asleep every night after two pages. So Why We Sleep really works! The book makes a very convincing case for the importance of sleep for our health, memory, performance and wellbeing. I finished it with mixed feelings as some recommendations are hard to follow. I do enjoy my vino and I have never been good at being lectured about the things I enjoy. If you don’t have a year just listen to the Joe Rogan Podcast with the author. It gives you a pretty good summary. Or just
- Clients see the certificate. This is the team behind it. Every year, our ISO 27001 team takes on the extra challenge of maintaining one of the highest standards in information security on top of their already demanding day jobs. A special thank you to K. Mink, who manages to keep us all moving through the endless procedures, evidence gathering, and reviews with patience, persistence, and a smile. And congratulations to K. Fah, who received the MVP Award from our external auditor. A fantastic and well-deserved recognition! Achieving
- Stress testing only works if you're stressing the right things. The ECB believes climate and nature-related risks still aren't being fully captured by many banks. According to ECB Vice-Chair Frank Elderson, physical and nature-related risks are "very likely being underestimated", despite significant progress in recent years. That's not entirely surprising. Nature risk, biodiversity loss, extreme weather, and long-term transition pathways are all difficult to quantify. Many banks are still building the data, models, and governance
This page shows public professional information only, each fact cited. Is this you? send a correction, or ask for removal within 24 hours, no questions asked.