Overview
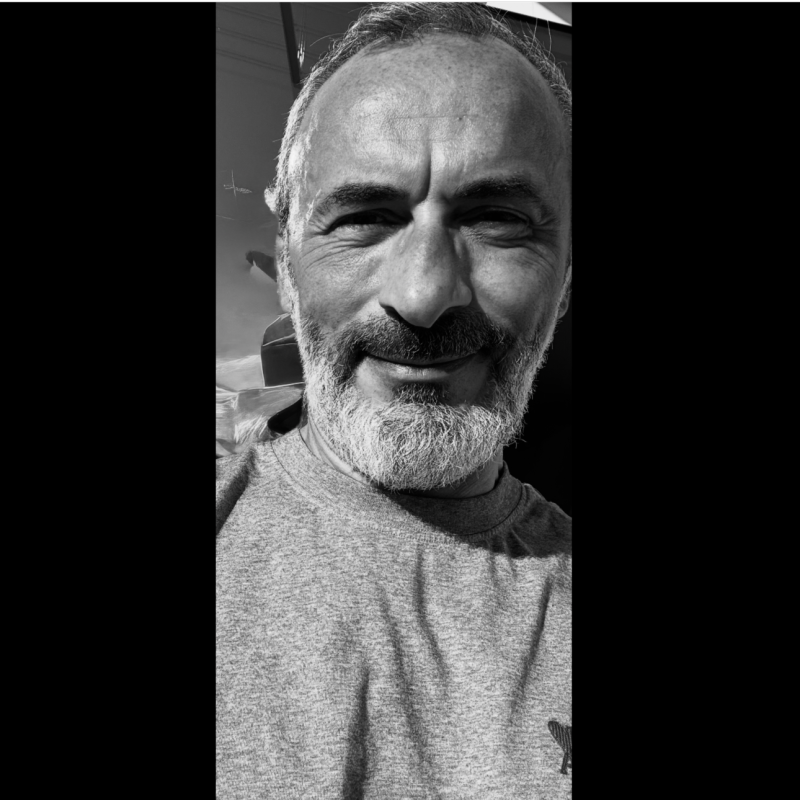
Jean-Gabriel Debaille is the founder of exthand and is based in Charleroi. He has been CEO and founder of EXTHAND since 2017. His stated areas of expertise are software development, payments, the payment industry, mobile payments and open banking.
Between August 2010 and July 2013 he was digital team leader at JWT Dialogue. Earlier, from June 1999 to March 2008, he was managing director of NETiKA, and from July 1995 to March 1997 he was a managing partner at the internet service provider NETLine.
He studied at Ichec Brussels Management School.
Career history

In the news
- Most Open Banking setups have one thing in common: a single provider standing between your platform and every payment or data flow. It works, until it doesn't. This piece looks at the architectural and availability risks nobody stress-tests until it's too late. Read on for what a resilient setup actually looks like. EXTHAND #A2A #openbanking #payment
- A European PSP just beat their full-year 2025 in six months. On rails they run themselves. 2025: ~€62M across ~100,000 payments. H1 2026: €200M+ across ~123,000 payments — and it's only July. That's the part I care about. Not that the number is big, but that it's compounding — and that it's theirs. We don't own their volume, their customers, or their brand. We're the connectivity layer underneath, doing one thing: keeping money moving without them having to think about us. When a PSP more than triples its run-rate and the hardest
- CCD2 compliance starts with data, not policy." I read that line recently and completely agree. But there's a second half worth adding: Your CCD2 audit trail is only as good as your data — and your data is only as defensible as the path it travelled to reach you. From November 2026, lenders and #BNPL providers must prove that every credit decision was grounded in documented, traceable evidence of a borrower's income, expenses and existing commitments. The #AIAct raises the stakes further: credit scoring is classed as "high risk,"
- Every open banking provider promises they won't monetise your customers' data. 😊 We took a different route: we built it so we never hold it in the first place. Most aggregators are SaaS. You call their API, they connect to the banks in your name, pull the data, store it on their servers, then send it back to you. Their pledge not to touch it is exactly that — a #pledge you have to trust. #Exthand's Evershield product isn't a SaaS platform. Evershield is a Docker container that runs inside your own cloud. Your customers' bank data
- We made a decision early on that sounds like bad business: we will never compete with our own customers. Most payment companies can't say that. The model is to build a network, put your brand at the checkout, and grow by pulling merchant volume onto your rail. It works — for the network. But every merchant on it is feeding the thing they depend on. Exthand is built the other way round. We're a technology supplier. White-label, behind the scenes. Your product at the front, your brand at the checkout, your customer relationship —
Related profiles
This page shows public professional information only, each fact cited. Is this you? send a correction, or ask for removal within 24 hours, no questions asked.