Overview
Luc Feyaerts is co-founder of c-site, a company he co-founded in August 2017, and is based in Gent. He founded LFT Consulting in July 2007 and Luc Feyaerts BVBA in July 2012, and has been managing director of both since. Since December 2019 he has sat on the advisory board of Co-libry.
At Voka - Kamer van Koophandel Mechelen-Kempen he has been a member of the board committee since January 2016, chaired the Lokaal Ondernemersnetwerk Mechelen from September 2016 to September 2018 and was vice-chair from September 2016 to April 2025. He was chief financial officer of COOP Apotheken from January to June 2026.
Feyaerts joined Intervest Offices & Warehouses in August 2008 as head of asset management and was chief operating officer from July 2012 until April 2017. Before that he spent eleven years at KPMG Tax Advisers Belgium, latterly as a director.
He studied law and corporate finance at KU Leuven, tax at the Université libre de Bruxelles, and completed several programmes at Vlerick Business School, including an executive MBA specialising in strategy and new business models.
Career history

In the news
- Recruiters mainly fish in the pool of 35-year-olds. That's what I hear regularly. They’re looking for agility: someone open to new frameworks, not set in old patterns. Fair enough. But is this really true? Agility isn’t proved by being young in my opinion. It’s proved by what you actually do. In 2024–2026 I completed an Executive MBA at Vlerick Business School. Magna cum laude, alongside people 15 to 20 years younger than me. Not as a career pivot, but as a deliberate choice to add rigour to what I’d been doing in practice
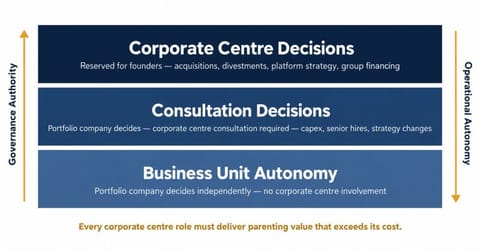
- ISMF – Component 4: Governance & Organisational Design Most governance failures in multi-business groups are not failures of intention. They are failures of design. The founder-dependent holding is the most common governance pattern in Belgian family-owned investment platforms. It works – until it doesn’t. The inflection point is predictable: somewhere between eight and twelve portfolio companies, the founders’ bandwidth runs out and the governance system collapses under its own weight. Component 4 of the ISMF is designed to
- Impressive C-SITE
- Most acquisition decks show a synergy number. Few track whether it ever materialised. After the deal closes, synergy commitments quietly disappear into the operational noise of running a business. Not because the logic was wrong. Because no one was ever made accountable for delivery. This is the problem Component 3 of the ISMF | Integration & Synergy Design is built to solve. But it starts with a constraint that most integration frameworks ignore: in a multi-business group operating through co-ownership and minority positions,
- ISMF – Component 2: Ownership Mode & Ecosystem Logic Most investment groups treat ownership structure as a deal outcome. The ISMF treats it as a strategic choice. The difference is consequential. When ownership mode is determined by what the deal allows rather than what the strategy requires, you end up with governance heterogeneity, insufficient rights, and management complexity that compounds with every new acquisition. In the ISMF, Component 2 answers two questions that most groups leave implicit: how should we own this business,
- The Integrated Strategic Management Framework – Component 1: Portfolio & Parenting Strategy Most holding companies and investment groups have a portfolio. Far fewer have a portfolio logic. The difference matters more than people think. A portfolio is a collection of positions. Portfolio logic is a set of explicit, repeatable criteria for deciding what belongs and what doesn't. In the ISMF, Portfolio and Parenting Strategy is the first component for a reason: every other design decision depends on it. You cannot design your
- Most corporate strategy frameworks were built with one assumption baked in: the corporate centre controls its portfolio through majority ownership and hierarchical authority. Pull on that thread, and you quickly realise how much of the strategic management literature simply doesn't apply to a large and growing category of real businesses such as family-owned investment platforms, holding companies with co-ownership structures, PE-backed groups operating through minority stakes, ecosystem builders who create value through
- An investment in knowledge pays the best interest." (Benjamin Franklin) Last Friday, I collected the receipt for one of the best investments I've ever made. And there is something wonderfully disorienting about receiving a Master of Business Administration in a football stadium. 🎓 With 25+ years in corporate finance, real estate and operations, I came in with a lot of experience. What Vlerick added was different: strategic thinking pushed well beyond the familiar, a much deeper look at leadership and what actually drives
This page shows public professional information only, each fact cited. Is this you? send a correction, or ask for removal within 24 hours, no questions asked.